What is a CVV Number?
What is a CVV number, and why do retailers ask for it? Find out where to find yours, how it protects you, and how to keep it secure.


What is a CVV Number?
A CVV number is a three- or four-digit security code printed on a card used to verify you have it in possession during a phone or online purchase.
Otherwise referred to as CVC (card verification code), CVV stands for ‘card verification value’ which is an important security feature for how credit cards work with online or over-the-phone payments.
Its main function is to protect you with card-not-present purchases, preventing fraud by checking the person making the purchase is in physical contact with the debit or credit card used for payment.
In this guide, we’ll unpack all you need to know about CVVs. From where to find them on different cards and how it protects against fraud, to how it differs from a PIN, when it’s safe to share your CVV, and what to do if it’s ever compromised.
Where to find your CVV number
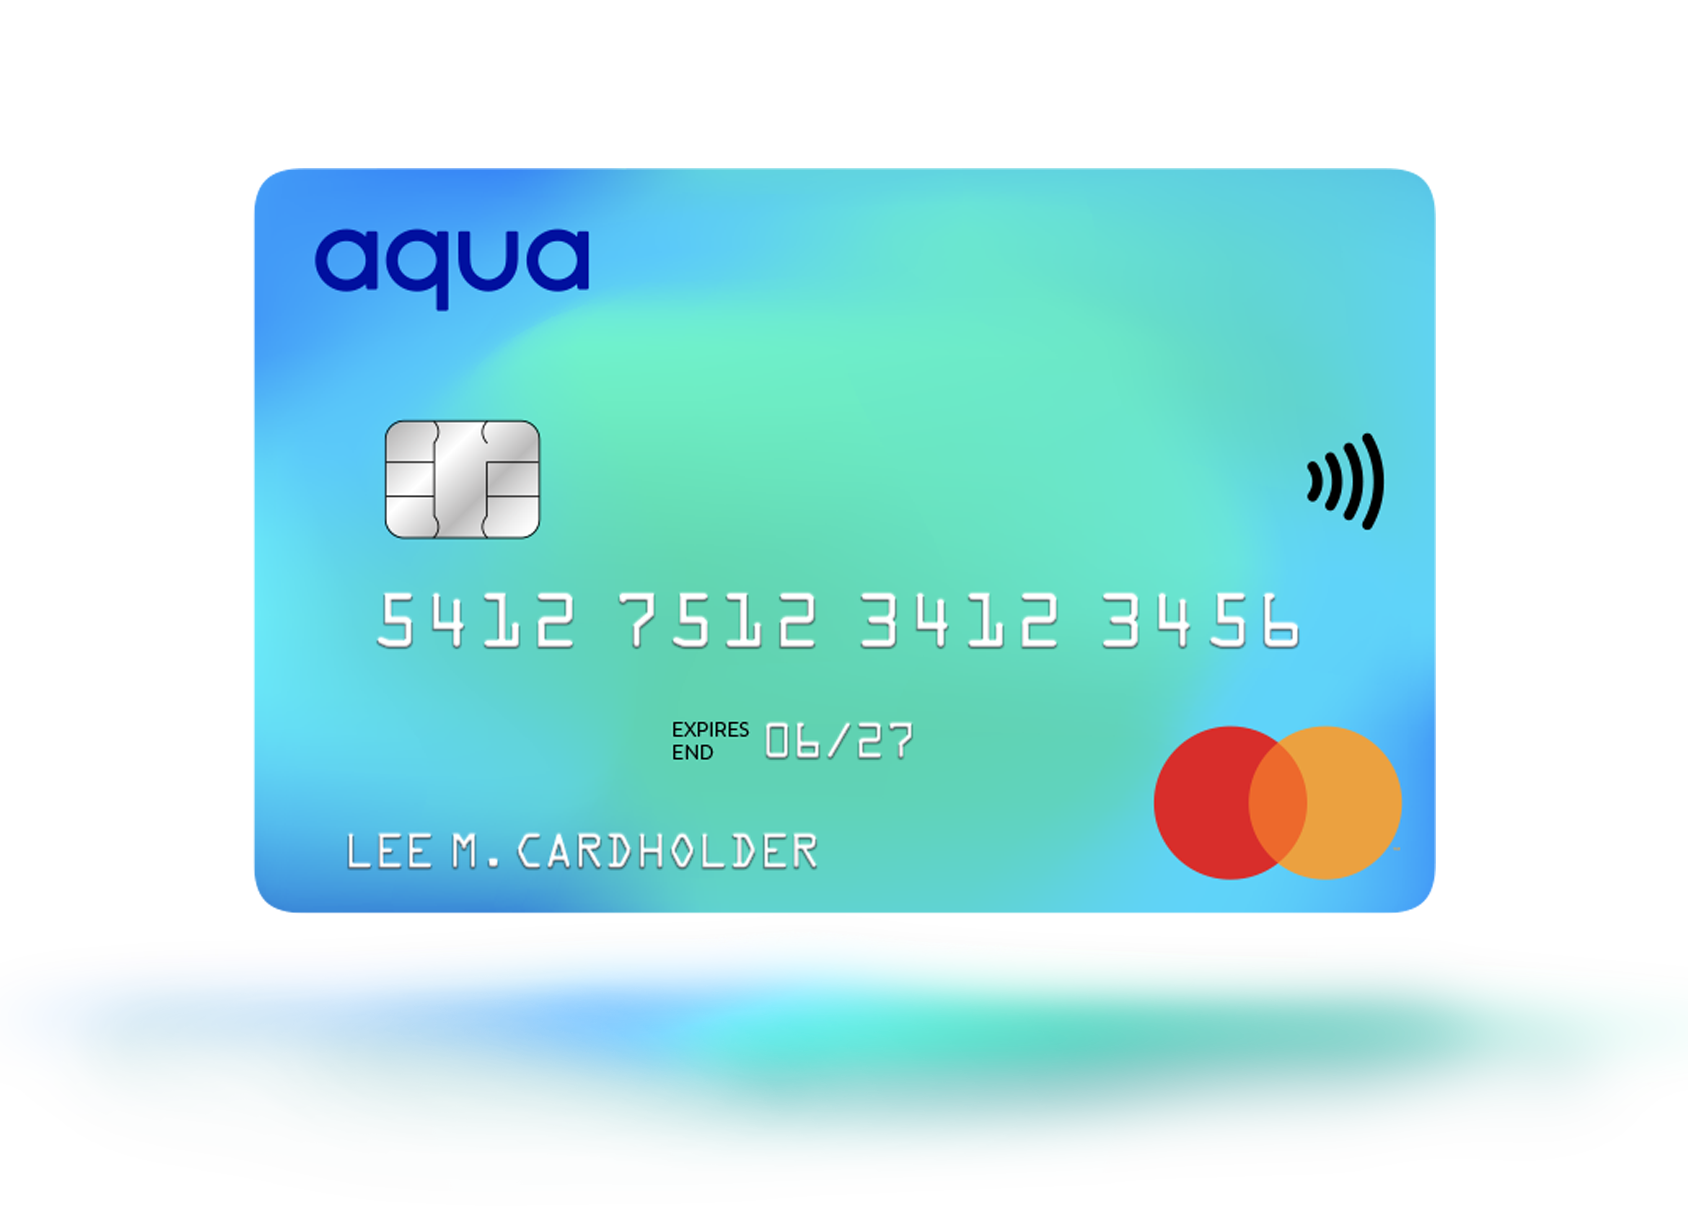
Where to find your CVV number will depend on the type of card. For a Visa or Mastercard, the three-digit security number is printed on the back of the card, usually to the right of the signature strip.
With other types of cards, such as American Express, you’ll find the CVV number printed above and to the right of the main card number on the front of the card. Whereas for debit cards, the number is usually printed on the back.
For digital and virtual cards, you’ll need to access your online account using your password or Face ID to locate your CVV number which is usually shared alongside the card number.
Wherever you find your CVV, it’s important to keep your details hidden from view and to only share it with trusted vendors or encrypted checkout pages.
It’s also reassuring to know a CVV isn’t embossed in your card’s chip or magnetic stripe data, so it can’t be read by a card skimmer and potentially be used for fraudulent activities.
What is a CVV used for?
A CVV is used as an extra layer of protection for online or over-the-phone purchases to prove the purchaser is in physical contact with the debit or credit card used for payment.
It’s one of several security features used by card providers to help you stay safe when shopping online. And by law, merchants are prohibited from storing your CVV once a transaction has been completed.
In some cases, a CVV is mistaken for a PIN. Although both act as security features, a CVV is usually only required for card-not-present purchases, whereas a PIN can be used for in-store purchases or to withdraw cash from an automated teller machine (ATM).
How does a CVV protect against fraud?
A CVV prevents the risk of fraud by adding an additional verification method for card-not-present transactions, such as paying for a family holiday over the phone or buying new furniture from an online store.
Even if a fraudster did gain access to a card number, completing an over-the-phone or online transaction would be unlikely without knowing the CVV. And because it’s not stored in the chip, stripe, or most transaction records, it’s harder for fraudsters to obtain a CVV than the card number alone.
Under card scheme rules, retailers aren’t permitted to store your CVV after a transaction is processed which further limits exposure should a retailer’s data become breached or compromised.
That said, a CVV alone doesn’t guarantee prevention against credit card fraud. You should always remain vigilant with over-the-phone and online transactions, and follow general online safety practices.
CVV vs PIN vs card number vs expiry date: what’s the difference?
There are many misconceptions relating to card numbers and their purpose. Here’s a comparison of the four most-used card details and when they’re likely to be used for in-person, over-the-phone, or online transactions.
CVV
A CVV is a three- or four-digit security code mainly used for card-not-present transactions to confirm the buyer has the physical card to hand. It could be an online purchase for new shoes or an over-the-phone transaction to pay a utility bill.
PIN
A PIN (personal identification number) is a changeable four-digit code used to authorise in-person chip-and-pin transactions and cash withdrawals. Unlike a CVV, a PIN will never be requested for over-the-phone or online purchases.
Card number
A card number is a unique 16- to 19-digit number that identifies your specific account. It’s printed on the front or back of your card and, although it’s needed for most online transactions, it’s not sufficient on its own.
Expiry date
An expiry date is a four-digit number showing the month and year your physical card will stop working for purchases. It’s often used alongside a CVV for over-the-phone or online payments.
Is it safe to share your CVV?
Sharing your CVV is safe provided it’s shared over the phone with a reputable merchant you’ve contacted directly, or on an encrypted website signified by a small padlock icon to the left of a website address starting with ‘HTTPS’.
You should never share your CVV in an email, text message, or with anyone who contacts you unexpectedly claiming to be your bank or card provider. It’s also never required for in-person transactions and could be a sign of fraudulent activity.
Other ways to keep your CVV safe is to never have it stored in unsecure notes, spreadsheets, screenshots, or any other way a fraudster could potentially gain access. Keeping it secure is a smart way to protect and manage your account.
What to do if someone has access to your CVV or card details
If you suspect someone has access to your CVV, card details, or you notice suspicious activity on your credit or debit card account, follow these steps straightaway to prevent potential further financial harm:
Step 1: Contact your lender immediately to block unauthorised transactions, limit your financial liability, and prevent further loss.
Step 2: Freeze your card by accessing your lender’s mobile app or online banking portal. Whichever’s easier for you.
Step 3: Check recent transactions for anything suspicious and report any unauthorised payments immediately.
Step 4: Request a new card and CVV to stop fraudsters potentially using your account details for future financial activities.
Under UK financial protections, you generally won’t be held liable for fraudulent transactions against your account provided they’re reported promptly. So, if something looks suspicious, contact your lender straightaway.
A CVV is a simple but important security feature designed to protect you when making card-not-present purchases, be it over the phone or online on a retailer’s website.
To keep your account safe, only share your CVV with trusted retailers you have contacted directly or encrypted websites that have measures in place to protect your financial information.
In no circumstances should you share your CVV in other ways, be it an email, text message, unsolicited calls, or even in a screenshot to your friends or family members.
If you want a credit card built with security in mind, explore our range of Aqua credit cards and learn how to use your card safely and securely.
Representative 39.9% APR (variable) on Aqua Classic
Contributors

You might also like
Slide 1 of 3
Your first credit card
Helping you to get started with your first credit card. From choosing the right card to building credit responsibly...

Should I get a credit card?
Wondering if you should get a credit card? A credit card can be incredibly useful, and with our helpful guide, you'...

How credit card payments work
Learn how credit card payments work, how and why credit card charges are applied and how to manage payments.
The smart way to build better credit
Aqua is the credit card that gives you the power to improve your credit score